China’s National Financial Regulatory Administration (NFRA) on 30 October issued the Measures for the Administration of Asset Management Trusts, NFRA Order No. 5 of 2026. The 85 articles take effect on 1 January 2027 and replace the rules on collective fund trust plans that the former banking regulator issued in 2007 and amended in 2009. The new text defines an asset management trust as a private asset management product, limits each product to 200 qualified investors, bans pooled products and channel business, and caps exposure to any single asset at 25% of a product’s net assets. In RegMemo’s analysis, the measures complete the move of China’s trust companies from credit channels for other institutions to private fund managers held to the same standards as other asset managers.
A 19-year-old rulebook gives way
In its question-and-answer note, the NFRA says the 2007 rules had been in force for 19 years and needed updating to reflect the reform and risk resolution work in the trust industry. It lists the documents the new measures sit on: the 2018 unified rules for asset management products, a 2023 notice that split trust business into asset management, asset service and charitable trusts, 2025 opinions on trust supervision forwarded by the State Council’s General Office, and the revised Measures for the Administration of Trust Companies issued the same year. A draft went out for comment from 31 October to 1 December 2025. The NFRA says it changed the final text on investor concentration, performance fees, the split of duties with distributors, liquidity management and the transition plan.
Who can buy, and how much
Products must be sold privately to qualified investors, with no more than 200 investors per product. An individual qualifies with at least two years of investment experience and either household net financial assets of RMB3 million, household financial assets of RMB5 million, or average personal income of RMB400,000 over the past three years. A company needs net assets of RMB10 million at the latest year end.
Minimum subscriptions rise with risk. An investor must put at least RMB300,000 into a fixed income trust, RMB400,000 into a mixed trust, and RMB1 million into an equity, commodity or derivatives trust, or into any trust whose underlying assets include non-standard assets such as private loans. A single investor may hold no more than 50% of a product’s units, and an institution and its affiliates no more than 80%.
Distribution is narrowed. For now only trust companies, commercial banks, insurers and securities firms may sell trust products, and the NFRA bars any other institution or person from doing so in disguised form. Trust companies must grade every product on at least five risk levels, and where a distributor’s grading differs, the higher grade applies. No seller may promise principal or returns.
Concentration limits now apply to the product and the firm
Each product may put no more than 25% of its net assets into one asset, counting a borrower and its related parties as one asset, and no more than 25% into any one asset management product. Bank demand deposits and government, central bank, policy bank and local government bonds are exempt. Products sold only to institutions that each invest at least RMB10 million, and index-tracking products, are among the exceptions.
Firm-wide limits sit on top. All of a trust company’s products together may invest no more than RMB30 billion in the same asset and may hold no more than 30% of a listed company’s tradable shares. Non-standard debt held by products with individual investors may not exceed 50% of the company’s total trust net assets. Borrowing is also capped: total assets may not exceed 140% of net assets in a structured product and 200% in other products.
The NFRA also closes the pooling route. A product that holds non-standard assets, directly or through another fund, must be closed-end, and those assets must mature or be exited by the product’s end date. Closed-end products must run for at least 90 days, and open-ended products must have dealing intervals of at least seven days. Each product needs its own accounts, and net values must follow accounting standards with no pricing that departs from the underlying assets. Products that hold non-standard assets and have individual investors need a product-by-product external audit of their net value calculations at least once a year.
Channel business is banned outright
Article 56 lists what a trust company may no longer do: provide channels that let others evade investment, borrowing or other limits; let investors, their nominees or an investment adviser run due diligence, issue investment instructions or execute trades. Private fund managers that act as advisers must have been registered with the Asset Management Association of China for at least a year, have a three-year track record and employ at least three investment staff. Performance fees are capped at 60% of returns above the contractual benchmark.
The measures also end an exemption for insurers. A clause in a 2019 notice that eased rules for insurance funds investing in AAA-rated collective trusts no longer applies.
The 25% single-asset limit matches the cap in the China Securities Regulatory Commission’s October draft on private fund-of-funds, so if that draft is adopted, trust products and private fund-of-funds will face the same diversification test.
What to watch
- 1 January 2027: the measures take effect, and all new trust business must comply.
- From 2027: trust companies must lock non-compliant legacy products, file rectification plans and shrink them; the NFRA will use progress in its classification of trust companies.
- Legacy products that breach the investor concentration or 25% limits may stop taking new money or buying new assets in place of immediate sale.
- 31 December 2029: deadline for open-ended products with dealing intervals under seven days to be wound down at maturity.
Primary sources
- National Financial Regulatory Administration, Measures for the Administration of Asset Management Trusts (Chinese), 30 October 2026
- National Financial Regulatory Administration, NFRA issues the Measures for the Administration of Asset Management Trusts (Chinese), 30 October 2026
- National Financial Regulatory Administration, Officials answer questions on the measures (Chinese), 30 October 2026
Related: China’s CSRC drafts rules for private fund-of-funds, capping any single fund at 25%
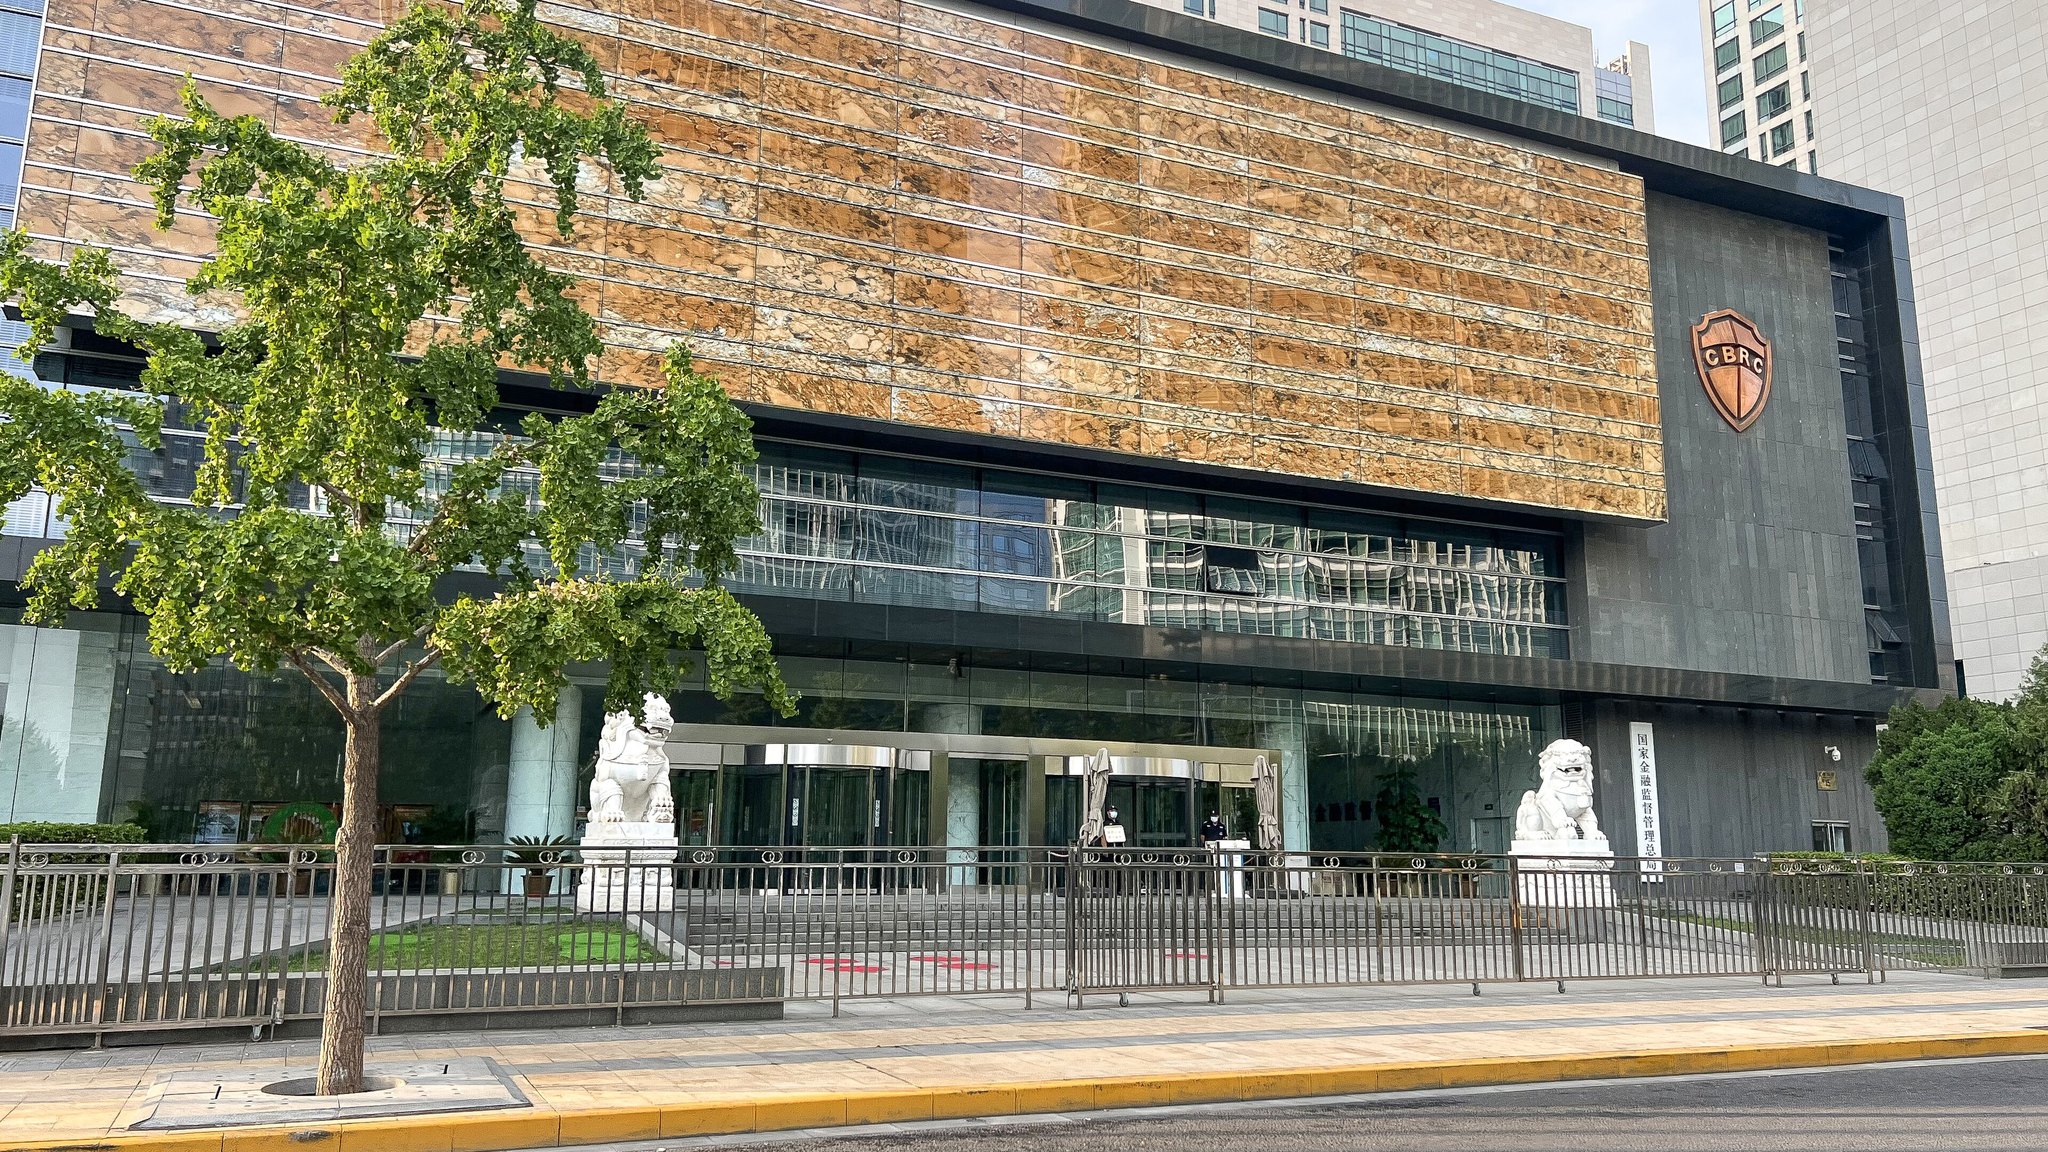
Photo (cropped): N509FZ, CC BY-SA 4.0 via Wikimedia Commons
